If you own an investment property in Australia, there's a good chance a significant part of your wealth is tied up in it. Your property's value may have increased since you purchased it, but that doesn't necessarily mean you have cash readily available when a major expense or investment opportunity comes along. For everyday property investors, accessing that equity can help fund renovations, cover unexpected property costs, build a financial buffer or contribute towards another property purchase. The challenge is finding an option that suits your finances, particularly when you want to keep your existing investment property and avoid unnecessary changes to your mortgage.
Australian mum and dad property investors can consider mortgage top-ups, refinancing, specialist non-bank finance and rental income advances to access capital from an investment property. The most suitable option depends on how much capital you need, your ability to qualify for additional lending, total funding costs and the impact on your ongoing rental income.This guide compares the available options, explains which circumstances they may suit and helps you understand the financial trade-offs before making a decision.
What is a mum and dad property investor?
In Australia, the term mum and dad property investor generally refers to an individual or household that owns one or a small number of investment properties. These investors typically manage their rental properties alongside their jobs, household expenses and other financial commitments. According to the Australian Housing and Urban Research Institute (AHURI), small-scale investors account for approximately 90% of Australian property investors.
The expression is commonly used to distinguish individual landlords from large institutional property investors. You don't need to be a parent to fall into this category. It's also different from the Bank of Mum and Dad, which refers to parents providing financial assistance to help their children purchase a home. If that's your situation, you can read our separate guide to the Bank of Mum and Dad in Australia.
For small-scale investors, property can represent a substantial part of their long-term financial strategy. However, owning a valuable investment property doesn't always translate into having available cash. Mortgage repayments, property expenses and household commitments can make accessing capital more complicated than the property valuation might suggest. That's where understanding your equity-release options becomes useful.
What does equity release mean for an investment property?
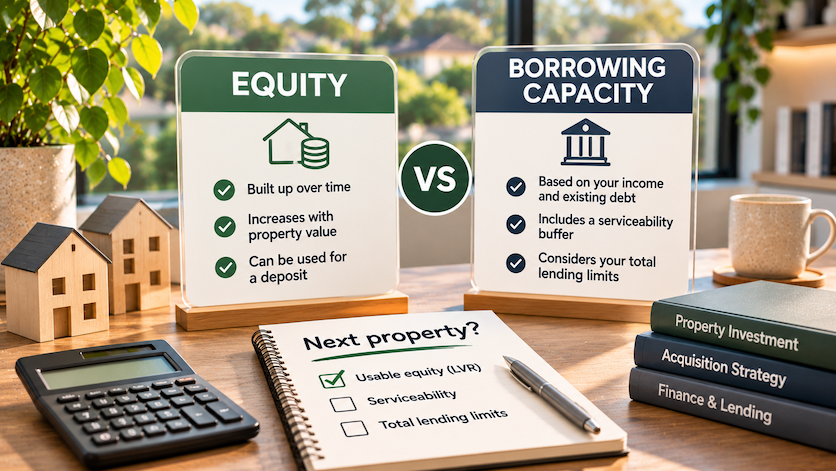
Equity is the difference between your investment property's current market value and the amount outstanding on its mortgage. For example, suppose you own a rental property worth $800,000 with a mortgage balance of $480,000. You have $320,000 in property equity, which may have accumulated through capital growth, mortgage repayments or both.
However, having $320,000 in equity doesn't mean you can withdraw that entire amount.
How much of your equity can you actually access?
Banks generally assess how much additional lending they can provide based on the property's valuation, loan-to-value ratio (LVR), your income, existing debts and ability to meet repayments. Using the same example, a lender allowing total borrowing up to 80% LVR would calculate:
- Current property value: $800,000
- Maximum lending at 80% LVR: $640,000
- Existing mortgage: $480,000
- Potential additional borrowing: $160,000
That $160,000 is an indicative amount based on the property's value and existing mortgage. The lender must still approve the additional borrowing, and the amount available could be lower. This distinction becomes particularly important for investors with substantial equity but limited borrowing capacity. A bank may decide that your income, household expenses and existing mortgages don't leave enough room to service more debt, even when the property provides sufficient security.
Australia's banking regulator, APRA, requires banks to assess mortgage serviceability using interest-rate buffers. Its guidance also expects lenders to make allowances for rental vacancies and uncertainty when considering investment property income. You can read more in our guide to equity versus borrowing capacity for property investors.
Which equity release services are available to Australian property investors?
There are several ways to access capital linked to an investment property. Some involve increasing your mortgage, while others use different funding arrangements. Before applying for additional capital, it's also worth checking whether you already have accessible funds in an offset account or redraw facility. Those funds may meet your immediate needs without arranging new finance.
1. Mortgage top-up through your existing bank
A mortgage top-up allows you to increase the amount borrowed against your existing property, subject to the lender's approval. For a property investor with substantial equity and sufficient income, this can be a relatively straightforward way to access capital without changing banks. Your lender may require an updated property valuation, income documents and an assessment of your existing financial commitments. If approved, the additional amount increases your mortgage balance and the repayments or interest you need to cover.
When might a mortgage top-up make sense?
A top-up may suit investors who have strong borrowing capacity, don't need the funds immediately and are comfortable taking on additional mortgage debt. For example, an investor planning a $30,000 renovation might choose a top-up if their existing lender offers competitive terms and they can comfortably afford the increased repayments. The total cost depends on the interest rate, loan structure and how long the additional amount remains outstanding.
A mortgage top-up doesn't automatically require extending your mortgage term. NAB explains that its top-ups generally retain the existing loan term and may not attract an application fee, although other lenders can have different requirements. For investors who qualify, checking with the existing bank is often a sensible starting point.
2. Refinancing your investment property
Refinancing involves replacing your existing mortgage with a new loan arrangement, potentially with a different lender. You may refinance to access additional equity, secure a more competitive interest rate, change your loan features or reorganise your existing mortgage arrangements.
For some investors, refinancing provides an opportunity to improve the overall cost or structure of their property finance while accessing capital for another purpose. However, refinancing usually requires a new credit assessment, supporting financial documentation and a property valuation. Depending on the lender and loan, there may also be discharge fees, switching costs or break fees.
When might refinancing make sense?
Refinancing may be appropriate when your existing mortgage is no longer competitive, you want to change lenders or you're planning a substantial restructuring of your property finances. It may be less attractive if you already have a favourable mortgage rate and only need a relatively modest amount of capital. You should also consider the total interest payable over the new loan term. Extending the period over which you repay the debt can increase its overall cost, even if the monthly repayments become more manageable.
3. Specialist non-bank property finance
Non-bank lenders provide an alternative to traditional bank mortgages. Their products can include investment property loans, second mortgages and specialist short-term finance. Some non-bank lenders may consider applications that fall outside a major bank's preferred criteria, including certain self-employed applicants, complex borrowing structures or time-sensitive property transactions.
However, the term non-bank covers a wide range of products. Many of these arrangements still involve borrowing money, providing property security and meeting the lender's credit assessment requirements.
When might specialist non-bank finance make sense?
An investor may consider specialist finance when a traditional lender cannot accommodate their circumstances or when timing is particularly important. For example, someone purchasing an investment property through an unusual ownership structure may need a lender with more flexible assessment criteria.
Specialist finance can involve higher interest rates, establishment fees or shorter terms than standard mortgage products. It's important to understand the total cost, security arrangements and repayment obligations before proceeding.
4. Accessing future rental income upfront through Futurerent
Futurerent offers eligible Australian property investors a way to access capital from their investment properties without refinancing or increasing their existing mortgage. Through Futurerent, investors can cash out up to $100,000 per eligible investment property, or up to $500,000 across multiple properties. The arrangement works by providing an upfront cash-out in exchange for an agreed portion of future rental income. Your tenant continues paying rent to your property manager as usual, and your property manager distributes the agreed portion to Futurerent.
You continue receiving the remaining rental income throughout the agreement. Futurerent uses property-based approval, rather than requiring the same personal income and expense verification typically associated with bank lending. Eligible investors can receive funds in as little as 2 business days, subject to approval. Applying for Futurerent involves a soft credit check with your consent, which doesn't affect your credit score.
When might Futurerent make sense?
Futurerent may suit investors who have equity in their investment properties but want to avoid refinancing, retain their existing mortgage arrangements or access capital more quickly. Investors may use their cash-out for renovations, property expenses, a financial buffer, another investment property deposit or other significant financial needs. However, Futurerent has an upfront setup cost and a fixed funding cost. The agreed portion of rental income allocated to Futurerent also reduces the rent you receive during the agreement.
That makes it important to check whether your remaining rental income can continue covering the property's mortgage payments and other expenses. You can use the Futurerent cash-out calculator to see an indicative amount, the associated costs and how much rental income you would continue receiving.
How do the equity release options compare?
Each option involves different approval requirements, financial commitments and ongoing costs.
The most appropriate option depends on what you need the capital for and how the arrangement affects your broader financial position.
For investors with strong borrowing capacity, traditional mortgage finance may offer relatively competitive funding costs. However, the lowest interest rate doesn't necessarily produce the best outcome if the loan remains outstanding for much longer than intended or requires changes to an otherwise favourable mortgage. For investors considering Futurerent, the important figures include the cash-out amount, setup cost, total fixed funding cost and amount of rental income retained throughout the agreement.
Which option suits your investment property situation?
Consider how the different funding arrangements might apply to four common situations faced by individual property investors.
Scenario 1. You need $20,000 to renovate your investment property
Suppose you own a rental property earning $650 per week. Your property manager believes some targeted improvements to the kitchen, flooring or bathroom could make it more appealing to tenants and potentially increase the weekly rent. You've received quotes totalling $20,000 but don't want to use your household emergency savings.
A mortgage top-up may be worth investigating if you qualify for additional lending and have sufficient time to complete the approval process. You could also compare available redraw funds or a Futurerent cash-out. Before selecting a funding option, calculate the potential return from the renovation.
If the improvements increase the rent by $50 per week, that's an additional $2,600 in gross annual rental income at full occupancy. You'll need to account for the renovation cost, funding fees, any vacancy during the works and other expenses before deciding whether the expected return is worthwhile. Your property manager can help assess realistic rental demand and the improvements most likely to make a difference.
Scenario 2. You need $40,000 for your next investment property
You already own an investment property and want to purchase another. You've identified a suitable opportunity, but need additional capital for the deposit and acquisition expenses. You have substantial equity in your existing property, although accessing it through the bank may require a mortgage top-up or refinance. Futurerent may provide an alternative way for an eligible investor to access capital without changing their existing mortgage.
However, obtaining deposit funds is only part of the purchase process. You'll still need a lender to approve the mortgage for the next property. That lender will assess your income, existing commitments, the expected rental income and its own lending requirements. If you plan to use Futurerent for a purchase, discuss the arrangement with your mortgage broker before proceeding. A future lender may consider the portion of rental income allocated to Futurerent when assessing serviceability.
Scenario 3. You receive an unexpected $15,000 strata levy
Large special levies can create significant financial pressure for apartment investors, particularly when they arrive alongside mortgage repayments, insurance and other holding costs. If you have sufficient cash reserves, you may be able to cover the levy without arranging additional finance. It may also be worth asking the owners corporation whether a payment arrangement is available. If you need capital, compare the options carefully, particularly the total cost of accessing a relatively small amount.
Futurerent's published setup cost for a cash-out up to $30,000 is $2,900 including GST, before the additional fixed funding cost. For a $15,000 expense, the setup cost alone represents a substantial proportion of the funds required. That doesn't automatically rule out a cash-out, but it makes comparing the full cost with other options particularly important.
Scenario 4. You want a financial buffer while holding your investment property
Higher mortgage payments, vacancies and unexpected property expenses can put pressure on your household finances. You may have an investment property with substantial equity but relatively little cash available for an unexpected repair or a period without rental income. A dedicated cash buffer can help you manage these expenses while maintaining your longer-term investment plans.
Before accessing additional capital, calculate how much of a reserve you realistically need. Consider mortgage payments, essential property expenses, possible vacancies and upcoming maintenance. You should also weigh the cost of accessing capital against the benefit of having it available. If funds remain unused, the financing costs still matter. For a more detailed approach, see our guide to managing investment property cash flow.
What does equity release actually cost?
When comparing funding options, it's important to consider the total dollar cost over the period you expect to use the capital. A mortgage top-up generally involves interest on the additional amount borrowed. Depending on the loan structure, you may also need to make principal repayments, and some of the debt could remain outstanding for many years. Refinancing may involve similar ongoing costs, together with potential switching expenses or changes to the existing mortgage.
Specialist non-bank finance can involve additional establishment costs, higher interest rates or specific repayment requirements. Futurerent uses a different cost structure, consisting of an upfront setup cost and a fixed funding cost through the allocation of future rental income. Its currently published setup fees are:
- Up to $30,000 cash-out: $2,900 including GST.
- $30,001 to $60,000: $3,900 including GST.
- $60,001 to $100,000: $4,500 including GST.
The total cost of a Futurerent cash-out also includes the fixed funding cost quoted for the arrangement. For example, if your investment property receives $650 per week in rent and a hypothetical arrangement allocated $200 per week to Futurerent, you would continue receiving $450 per week before mortgage payments, property management fees and other expenses.
This is an illustrative rental allocation rather than an actual Futurerent quote. The amount of capital returned through the rental income allocation includes the upfront amount and the agreed funding cost. You should therefore distinguish the total rental allocation from the funding cost itself. Our separate guide to mortgage top-ups versus rental income advances explains the financial comparisons in greater detail.
Does equity release affect your credit score or borrowing capacity?
The impact depends on the funding arrangement. When you apply for a new mortgage or increase an existing loan, your lender will generally assess your credit history, income, expenses and existing commitments. Additional borrowing may affect the amount of further debt you're able to service. Futurerent doesn't increase your existing mortgage, and its application process uses a consented soft credit check that doesn't affect your credit score.
However, credit scores and mortgage borrowing capacity are different considerations. When assessing a future mortgage application, a bank may take account of the rental income allocated to Futurerent. That could affect how much rental income is available for servicing the proposed mortgage. Different lenders may assess these arrangements differently, so investors considering another property purchase should discuss their plans with a mortgage broker.
Are there any tax considerations?
The tax implications of accessing property equity depend on the funding structure and how you use the money. For traditional mortgage borrowing, the Australian Taxation Office generally considers the purpose of the borrowed funds when determining whether interest expenses are deductible. For example, money borrowed to renovate an income-producing investment property can receive different tax treatment from money borrowed for a personal expense, even where the same property secures the mortgage.
Futurerent uses a different arrangement and has obtained an ATO product ruling covering relevant aspects of its structure. Your accountant can review the ruling and explain how it applies to your circumstances. You should keep records of the funding arrangement, associated expenses and how the capital was used. If your property is jointly owned or held through a company or trust, also check the provider's eligibility criteria and any legal or tax considerations before proceeding.
Is equity release the same as a reverse mortgage?
When searching for equity-release services in Australia, you may encounter reverse mortgages and other retirement-focused equity-release products. These products are generally designed for older homeowners seeking to access capital from the home they live in. According to ASIC's Moneysmart, reverse mortgages and related products can have significant long-term financial implications.
They address different circumstances from those of a property investor seeking to access capital from a residential rental property. For investors who want to maintain ownership of an income-producing property, mortgage top-ups, refinancing, specialist investment-property finance and rental income advances are generally more directly relevant options to investigate.
How to choose the right equity release service for your investment property
Before applying for any equity-release arrangement, start by understanding why you need the capital and how it will affect your finances. Consider the amount required, whether the expense is temporary or ongoing, and how much you can comfortably contribute from your existing savings. Then compare what each provider can offer, including the full cost, approval requirements, funding timeline and any changes to your mortgage or rental income.
If you're considering another property purchase, speak to your mortgage broker about your borrowing capacity before committing to additional capital. If you're planning a renovation, ask your property manager to assess the achievable rental income and likely benefits of the improvements. For investors facing ongoing cash-flow difficulties, accessing capital may provide temporary relief, but it won't necessarily resolve underlying holding costs. It's important to assess whether the property remains affordable after the funds have been used.
The aim is to choose an arrangement that supports your investment goals while keeping your broader finances manageable.
Frequently asked questions
Are mum and dad property investors eligible for equity release?
Potentially, yes. Individual investors who own one or a few rental properties may be eligible for mortgage top-ups, refinancing or alternative arrangements such as Futurerent. Approval depends on the property's equity, the lender or provider's assessment criteria and your individual circumstances.
Which equity release service is best if I don't want to refinance?
If you have sufficient accessible funds in an offset account or redraw facility, those may be worth reviewing first. A mortgage top-up with your existing lender may also avoid a full refinance, subject to approval. Futurerent offers eligible investment property owners a way to cash out without changing their mortgage, although its setup cost and fixed rental income allocation need to be considered.
Can I release equity if the bank won't approve another loan?
Some providers offer arrangements with different eligibility requirements from traditional banks. Futurerent uses property-based approval rather than a conventional mortgage serviceability assessment. However, the investment property still needs to meet Futurerent's criteria, and approval isn't guaranteed.
Can I access equity from more than one investment property?
Yes, depending on the provider and the property's eligibility. Futurerent allows eligible investors to cash out up to $100,000 per investment property, with a maximum of $500,000 across multiple properties. Other providers may apply different limits and assessment requirements.
Does Futurerent affect my credit score?
Futurerent uses a soft credit check with your consent, which doesn't affect your credit score. Future mortgage borrowing capacity is a separate consideration, as a lender may assess the portion of rental income allocated to Futurerent when determining your ability to service additional debt.
Can I use equity release to help my children buy a home?
Depending on the funding option, investors may access capital to help their children with a deposit or other expenses. However, the tax, lending and legal implications depend on the arrangement and whether the funds are provided as a gift or loan. You can learn more in our Bank of Mum and Dad guide.
Find out how much capital you could access from your investment property
Owning an investment property can provide financial opportunities beyond the rental income you receive each month. If you need capital for renovations, major expenses, another property purchase or a financial buffer, there are several options worth exploring before making changes to your investment portfolio. Futurerent helps eligible Australian property investors cash out up to $100,000 per property without refinancing, with the upfront amount returned through an agreed portion of future rental income.
See how much capital you could access from your investment property.
Use the Futurerent cash-out calculator to see your indicative cash-out amount, the associated costs and how much rental income you would continue receiving.
This article provides general information only and does not constitute financial, credit, tax or legal advice. Consider your circumstances and seek appropriate independent professional advice before making a property investment or financing decision.