You need another $50,000 for your investment property. It might be for renovations, a deposit on your next purchase or an expense that has arrived sooner than expected. If your property has built up equity, you may be able to access that capital by increasing your mortgage. You may also be considering a rental income advance that lets you cash out without refinancing.
Both options put money in your hands, but they affect your finances in different ways. A mortgage top-up increases the amount you owe your lender, while a rental income advance such as Futurerent provides capital upfront in exchange for an agreed portion of future rent. The amounts you pay, how quickly you can access funds and how much money remains available each month can vary considerably.
For investors who qualify for both options, a mortgage top-up may have a lower direct funding cost, particularly when the additional borrowing is repaid promptly. A rental income advance can be useful when you want to keep your mortgage unchanged or need a simpler, property-based assessment. The right decision depends on your own numbers and how you intend to use the funds.
How does a mortgage top-up work?
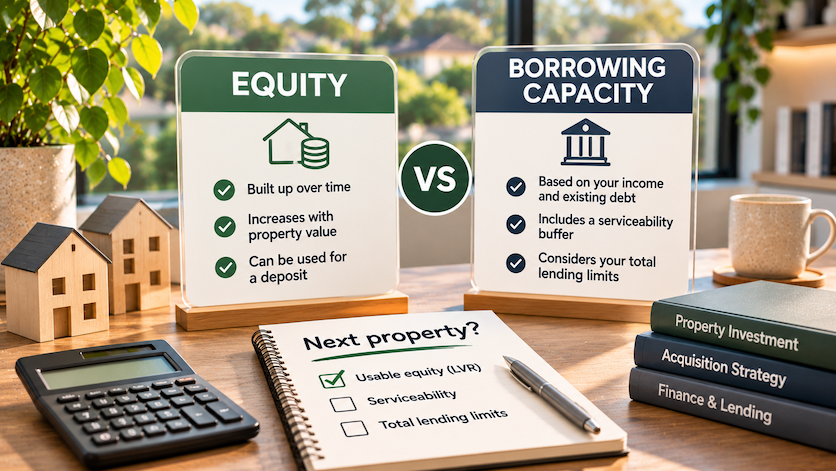
A mortgage top-up lets you borrow additional funds against the equity in a property you already own. For example, if your investment property is worth $900,000 and your outstanding mortgage is $550,000, there is $350,000 in equity before accounting for the lender's borrowing limits. The amount you could actually access depends on the property valuation, loan-to-value ratio, existing debts and your ability to afford the increased mortgage.
A top-up doesn't always require a complete refinance or a change of lender. Depending on your loan type, you may be able to increase an existing variable-rate mortgage or set up a separate loan split with your current bank. NAB explains that a top-up generally leaves the loan term unchanged, and that some top-ups do not attract fees. Other lenders may have different requirements or charges.
Your bank will usually assess your financial position again before approving the extra borrowing. You may need current income evidence, household expense details, existing debt information and an updated property valuation. Westpac's guidance describes these checks, including the lender's review of your credit history and capacity to manage higher repayments.
How does a rental income advance work?
A rental income advance gives an eligible property investor access to capital from an investment property's future rental income. With Futurerent, you receive an agreed cash-out amount upfront. Your property manager continues collecting the tenant's rent, directs a fixed portion of the rent collected to Futurerent and sends the remainder to you during the agreement.
Futurerent is structured through a concurrent lease rather than an increase to your mortgage. The existing mortgage balance and lender relationship remain unchanged, and the Futurerent application uses a soft credit check that does not affect your credit score. Futurerent assesses the property and rental arrangements rather than requesting personal income and expense statements. It can provide up to $100,000 per eligible investment property and up to $500,000 across a portfolio, subject to eligibility and approval.
There are two costs to understand. Futurerent charges an upfront setup cost, and it receives an agreed amount of rental income above the capital advanced as its fixed funding cost. The usual term is three years. If a property is vacant or the tenant falls into arrears, the rental allocation pauses when no rent is being collected, without increasing the agreed total funding cost. You should still consider how the reduced rent available to you during the arrangement affects mortgage payments and property expenses.
For more detail on the structure, see our guide to rental income advances.
Mortgage top-up vs rental income advance at a glance
The main differences extend beyond the funding cost. Your mortgage structure, serviceability position, rental income and the time available to obtain funds are all relevant. The following comparison reflects the general product structures, although exact terms depend on the lender or provider.
It is also worth distinguishing a mortgage top-up from a full cash-out refinance. A top-up with your existing lender may be much simpler than moving the entire mortgage to a different lender. If you are comparing Futurerent against a bank, ask the bank about an increase or separate split before assuming you need to replace your entire loan.
How much does each option cost over three years?
Consider three investors who each need access to capital for a different purpose. To keep the comparison consistent, the examples use an illustrative bank mortgage rate of 6.50% per year and an illustrative Futurerent rental income cost of 8.00% per year on the cash-out amount, fixed for three years. The Futurerent setup costs use the tiers currently published on its website. These are scenarios for comparing the mechanics, not personalised offers or guaranteed current pricing.
The mortgage examples assume an interest-only top-up with an unchanged balance for three years, a constant interest rate and no bank establishment fee. This makes the three-year interest cost easy to compare with Futurerent's fixed rental income cost. A bank may charge fees, require principal-and-interest payments or offer a different interest rate. The additional mortgage principal would also remain owing after three years under the interest-only assumption.
At $50,000, the mortgage top-up costs $9,750 in interest over three years under these assumptions. The Futurerent example costs $12,000 in fixed rental income above the amount advanced, plus a $3,900 upfront setup cost, making its total funding cost $15,900. That is $6,150 more in direct funding costs than the interest-only bank example, before any bank fees or tax effects are considered.
Those figures don't mean the bank option has finished after three years. With interest-only payments, you would still owe the full $50,000 top-up, whereas Futurerent would have received the agreed $62,000 of rent over the three-year term if rent was collected as expected. The cash-flow comparison therefore matters just as much as the headline cost, especially if you plan to hold the investment property for many more years.
What happens to your monthly cash flow?
Suppose your property receives $800 in weekly rent and you need a $50,000 cash-out. That produces about $3,467 in gross rent per month, assuming 52 weeks of rent over a year. The following figures focus on the additional funding arrangements and exclude existing mortgage payments, property management fees and other property expenses, which you would still need to cover.
If you use a mortgage top-up
At an illustrative 6.50% interest rate, a $50,000 interest-only top-up adds around $271 per month in interest payments. Your property manager still distributes the normal rental income, subject to their usual fees and expenses, but you have an additional mortgage payment to make. That payment could rise if the top-up has a variable interest rate.
If the bank instead requires principal-and-interest payments on a new $50,000 loan split amortised over 30 years at 6.50%, the indicative payment would be about $316 per month. Over the first three years, you would pay approximately $9,586 in interest and reduce the top-up balance to about $48,209. The longer loan term makes the monthly payments easier to manage, although leaving the balance in place for many years can materially increase the eventual cost.
If you use Futurerent
With a $50,000 cash-out and the illustrative 8.00% annual rental income cost, Futurerent would receive $62,000 from rent over three years. Assuming rent is collected as expected, that works out to about $1,722 a month of rent allocated to Futurerent, leaving around $1,744 of the original $3,467 in gross monthly rent before normal property expenses. You would also need to pay the separate $3,900 setup cost upfront.
The full $1,722 monthly allocation is not the funding cost. It contains the return of the $50,000 received upfront as well as the $12,000 fixed rental income cost. Nevertheless, it is a substantial reduction in the money you receive from the property each month. If your existing mortgage and expenses already consume most of the rental income, you will need other funds available to cover the difference.
These figures also assume a suitable investment property and sufficient rent for the proposed cash-out. The amount Futurerent can approve depends on the property's rental income and equity, and it cannot allocate more than the permitted proportion of expected rent. Use the Futurerent calculator for an estimate based on your actual property.
Three situations where the comparison changes
1. You're planning a $30,000 investment property renovation
Imagine you're preparing a kitchen and flooring upgrade in six months. You have enough time to request a mortgage review, gather documents and compare the additional borrowing cost. Under the illustrative three-year comparison, a $30,000 top-up costs $5,850 in interest if you pay interest only, while the Futurerent example has a total fixed funding cost of $10,100 including setup.
If the lender will approve the top-up at a competitive rate and the resulting payments are affordable, the bank option may make financial sense. You could also plan to reduce the extra mortgage balance faster if the renovation increases rental income. A Futurerent cash-out may still appeal if keeping the mortgage unchanged matters to you, but the higher direct funding cost deserves consideration when there is no pressing deadline.
2. You need $50,000 to move on a time-sensitive purchase
Now imagine your buyer's agent has identified a suitable investment property, but you need additional capital for the deposit and acquisition costs within a short window. Your current lender may be able to provide the funds, but there is no universal approval timeframe. Serviceability checks, valuation requirements and document processing could affect how quickly a top-up becomes available.
Futurerent's property-based process may be worth exploring if you have an eligible professionally managed rental property and need the cash quickly. Eligible investors can receive funds within two business days after approval, signing and payment of the setup cost. The additional direct cost in the $50,000 example is $6,150 compared with the assumed interest-only top-up, which gives you a concrete figure to weigh against the value of having capital available sooner.
If you plan to use that capital as a deposit for another property, speak with your mortgage broker before committing. The next lender may have rules about accepted deposit sources and may assess the rental income allocated to Futurerent when calculating your future borrowing capacity.
3. You need $80,000 for major property works or a financial buffer
A larger amount can place greater pressure on cash flow whichever option you choose. In the three-year examples, an $80,000 interest-only mortgage top-up costs $15,600 in interest, while the illustrative Futurerent arrangement costs $23,700 including its $4,500 setup cost. The $80,000 Futurerent advance would also require $99,200 of future rent to be allocated over the term.
For a property earning $1,000 a week, that allocation is roughly $636 per week on average, leaving around $364 of gross weekly rent before expenses. This may be workable for an investor with other income and a planned use for the capital, but it is a significant cash-flow commitment. If the property has limited rental income or the investor needs the cash simply to cover an ongoing monthly shortfall, neither option should be assumed to solve the underlying problem.
How do speed and paperwork compare?
A bank top-up usually involves an assessment of your financial position even if you are already an established customer. Lenders may request payslips, tax returns for self-employed applicants, living expenses, debt statements and an updated property valuation. Some lenders can complete straightforward applications more quickly than others, so ask yours for a realistic timeframe based on the documents and loan type involved.
Futurerent asks for basic investor and property information and works with the property manager to obtain the lease and management agreement. It also conducts a soft credit check with your consent. The application process is designed to be simpler than mortgage lending, although approval still depends on the property's eligibility, supporting documents, executed agreement and payment of the setup cost. Funds are typically transferred within two business days after those steps are complete.
Speed is valuable when a funding deadline is genuinely important. However, if the expense is planned several months in advance, it may be worth taking the time to pursue the lower-cost option available to you rather than paying more for speed you don't need.
Could a mortgage top-up cost more in the long run?
Yes, particularly if the extra borrowing stays on your mortgage for many years. A top-up that looks inexpensive over the first three years can continue accruing interest until you repay the principal. If you stretch the extra borrowing over a long principal-and-interest term, you might have manageable monthly repayments while paying a much larger total amount of interest over time.
For perspective, a standalone $50,000 principal-and-interest loan at a constant 6.50% over 30 years has an indicative repayment of about $316 per month and approximately $63,773 in total interest over the full term, excluding fees. That is a mathematical illustration, not a prediction of what an actual mortgage will cost. It also assumes you never make extra repayments and the interest rate never changes.
Futurerent's fixed cost is agreed upfront, so the funding cost does not rise because interest rates change or the property becomes temporarily vacant. However, you are giving up a meaningful portion of future rent during the arrangement and paying an upfront setup cost. Comparing a three-year rental advance with 30 years of bank interest without considering the very different repayment schedules can give the wrong impression of relative value.
Moneysmart recommends looking at both repayment amounts and total loan costs, including how the loan term changes the amount of interest paid. The most useful bank comparison is the extra borrowing you would actually arrange, with the repayment schedule you are likely to follow.
What about tax and future borrowing capacity?
The tax treatment of mortgage interest generally depends on how the borrowed money is used, rather than which property secures the mortgage. For example, the ATO's interest deductibility guidance explains that the use of the borrowed funds is central to determining whether the interest is deductible. Interest related to income-producing investment property expenses may be treated differently from interest on money spent for private purposes.
Futurerent uses a different legal structure, and its tax treatment should not be assumed to match bank loan interest. Ask a registered tax agent to assess your intended use of the funds and the relevant agreement before calculating any after-tax comparison. Keep clear records if the capital will be used for both investment and personal purposes.
Future borrowing also matters. A mortgage top-up increases your outstanding debt and regular mortgage commitments, which may affect subsequent lending assessments. Futurerent does not increase the existing mortgage or affect your credit score, but another lender may take account of the rental income that will be allocated to Futurerent. We explain that in more detail in our rental income advance guide.
Five questions to ask before choosing a funding option
Before applying, put both options on the same page using the amounts and terms available to you. This is particularly useful if you are comparing a bank's initial repayment estimate with Futurerent's rental allocation, because those figures represent different things.
- How much usable capital will I receive? Allow for any upfront setup fees and check whether you need extra cash to cover them.
- What is the total cost over my expected funding period? Include interest, establishment fees and fixed rental income costs, then model the mortgage balance that will remain.
- What happens to my monthly cash flow? Include mortgage payments, the rent you will retain, rates, insurance, property management fees, maintenance and vacancies.
- How quickly do I actually need the funds? Obtain a realistic bank timeframe before paying more for an alternative that may be faster.
- Will this affect my next financial move? Consider future mortgage applications, access to savings, renovation plans and whether you intend to pay down the extra borrowing early.
You can also compare these options with savings, existing redraw funds or an offset account if you have them available. Those may avoid a new funding agreement, although using the money could reduce your financial buffer or increase the interest on your existing mortgage.
When might Futurerent be worth considering?
Futurerent may be relevant if you have an eligible investment property, want to access capital without refinancing and prefer to keep your existing mortgage unchanged. The property-based assessment can also be useful for investors who would rather avoid a new bank serviceability assessment or do not want to provide personal income and expense statements as part of the cash-out process.
Eligible investors can cash out up to $100,000 per property or $500,000 across a portfolio. The amount available, setup cost, fixed funding cost and portion of rent allocated depend on the property and the agreed terms. You should assess whether the rent remaining after the allocation will comfortably cover the property's existing expenses and how the arrangement fits your longer-term plans.
For investors who can access a low-cost mortgage top-up and comfortably manage additional borrowing, that may be the more economical choice. If the bank route is unavailable, too slow or requires changes you would rather avoid, a Futurerent cash-out gives you another option to compare.
Frequently asked questions
Is a mortgage top-up the same as refinancing?
No. A mortgage top-up increases the funds borrowed, often through your existing lender, while refinancing typically replaces an existing mortgage. You can sometimes arrange a top-up or separate split without moving lenders, depending on the product and the bank's approval criteria.
Is a rental income advance cheaper than a mortgage top-up?
It depends on the amount, mortgage rate, fees, repayment schedule and length of time you keep the additional debt. In the three-year illustrations above, the bank has a lower direct funding cost, although the mortgage principal remains outstanding under an interest-only arrangement. Ask for individual figures before deciding.
How quickly can Futurerent provide funds?
Eligible investors can typically receive funds within two business days after approval, executed documents and payment of any setup cost. The exact timing depends on the property, documentation and approval process.
Do I need personal income documents to use Futurerent?
Futurerent uses a property-based assessment and generally does not require personal income and expense statements. Identity checks and property information are still required, and Futurerent works with your property manager to confirm the relevant rental arrangements.
What happens if my tenant stops paying rent?
With Futurerent, the allocation pauses when there is no rent being collected. The agreed total funding cost does not increase because of a vacancy or tenant arrears. With a mortgage top-up, scheduled repayments generally remain due even if the investment property is temporarily vacant.
Could either option affect my ability to borrow again?
Yes. A mortgage top-up increases mortgage debt and repayments. A Futurerent arrangement can reduce the rental income available for a future lender's serviceability calculation, even though it does not change your existing mortgage or credit score. Ask your mortgage broker to assess any planned future borrowing.
Compare the total cost before accessing your property equity
A mortgage top-up and a rental income advance can both help you fund a renovation, prepare for another purchase or meet a major expense while keeping your investment property. Their cost structures and impact on future cash flow are different, so it is worth comparing them with realistic assumptions and your own property numbers.
If you want to leave your existing mortgage in place, use Futurerent's cash-out calculator to see how much capital you may be able to access, the indicative fixed costs and the amount of rental income you would continue receiving. You can then compare those figures against a written top-up quote from your lender or mortgage broker.
This article is general information only and does not constitute personal financial, credit, legal or tax advice. All financial figures are illustrative, exclude tax effects and are not product quotations. Actual lender rates, fees, eligibility and Futurerent pricing may differ. Seek advice suited to your circumstances before entering a financial arrangement.