If you're planning to buy another investment property or refinance an existing mortgage, you may be wondering whether accessing rental income upfront will affect your next home loan application. It's an important question, especially if you're considering using a rental income advance to fund a deposit, renovation or other property expense.
A rental income advance can affect future mortgage borrowing capacity, depending on how your lender assesses the arrangement. With Futurerent, applying does not affect your credit score and your existing mortgage stays in place. However, a future lender may consider the portion of rent allocated to Futurerent when assessing how much income you have available to service another mortgage.
The practical effect depends on your income, existing financial commitments, the amount of rent allocated and the lender's credit policy. Understanding these factors before you access capital can help you plan your next purchase with fewer surprises.
Why credit score and borrowing capacity are different
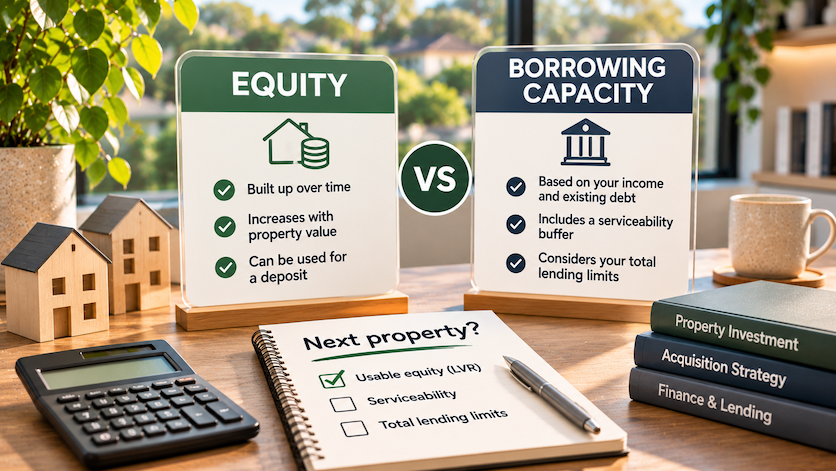
Credit score and borrowing capacity are often discussed together, but they answer different questions. Your credit score reflects information in your credit report, including aspects of your borrowing and repayment history. A lender's serviceability assessment looks more broadly at whether you could afford the mortgage you're applying for, based on your income, expenses and financial commitments.
As Moneysmart explains, your credit report and score may influence a lender's decision, but they do not establish how much you can afford to borrow. A strong credit score is useful, although it cannot guarantee approval if your available income is insufficient for the new mortgage.
What happens to your credit score with Futurerent?
Futurerent uses a soft credit check with your consent. According to Futurerent's published product information, this does not create a hard credit enquiry on your record or affect your credit score. The cash-out also does not increase the balance of your existing mortgage, because Futurerent accesses an agreed portion of future rental income through a different arrangement.
That can matter if you want to keep your existing mortgage unchanged. However, another lender's assessment goes beyond what appears on your credit report and will also take account of the income and commitments relevant to your new application.
How does a lender calculate borrowing capacity?
When assessing a mortgage application, a lender typically looks at salary and other income, current mortgage repayments, personal debts, living expenses and the costs of owning your properties. Lenders also consider whether you could continue making repayments if interest rates increased or your circumstances changed.
For banks regulated by the Australian Prudential Regulation Authority (APRA), the mortgage serviceability buffer is currently at least three percentage points above the loan interest rate. APRA also provides guidance on allowing for fluctuations in rental income. Its residential mortgage lending guidance recommends applying a discount of at least 20% to expected rental income as a prudent approach, with higher discounts where appropriate. The exact way a bank calculates serviceability is determined by its own lending policy and the applicant's circumstances.
How a rental income advance can change the income available to a future lender
With Futurerent, an eligible property investor receives an agreed amount of capital upfront. Their tenant keeps paying rent to the property manager, who directs an agreed portion of the rent collected to Futurerent and distributes the remainder to the investor. The arrangement generally runs over a three-year term, although the exact figures depend on the agreement.
Your property may still be earning the same gross rental income during that period. However, you're receiving less of that rent directly because part of it has been allocated under the Futurerent agreement. When you later seek another mortgage, a lender may take that allocation into account when assessing your available rental income or financial commitments.
There is no single calculation that applies to every bank. A lender might assess the amount of rent actually available to you, examine the rental allocation as an ongoing commitment, request more documents about the agreement or apply another approach permitted by its credit policy. This is why an individual borrowing-capacity assessment is more useful than a general promise about eligibility.
A worked example of how rental income could be assessed
Consider an investor whose property rents for $800 per week. They enter a rental income advance arrangement under which $200 per week of the rent collected is allocated to the provider. The investor continues receiving $600 per week before the usual property expenses, assuming the property remains tenanted and rent is paid in full.
To illustrate the possible effect on a mortgage assessment, the table below applies a hypothetical 20% rental-income discount before and after the allocation. This is a simplified illustration based on the discount discussed in APRA's guidance, and assumes the lender assesses only the rent remaining available to the investor after the allocation. It is not a calculation of what any particular bank would approve.
Under this illustrative method, the income included in the lender's assessment falls from $640 to $480 per week, or by $8,320 per year. The change in assessed income is not the same as the reduction in maximum borrowing capacity. A bank would still need to consider your salary, other rental income, property expenses, existing mortgages, future loan repayments and applicable lending policies.
The figures also highlight why you should distinguish the property's gross rent from the rent available to you during the advance. If you're hoping to purchase another property soon, ask your broker to model your borrowing position both before and after the proposed allocation using the actual terms you're considering.
Could a rental income advance make it harder to get another mortgage?
It could in some circumstances, particularly where you already have limited surplus income for servicing another loan. If a lender recognises less available rental income during your Futurerent agreement, you may qualify for a smaller loan than you would have without that allocation. You may also need to provide additional information so the lender can understand how the arrangement affects your cash flow.
That does not mean an advance automatically prevents you from obtaining another mortgage. An investor with substantial employment income, manageable debts and a strong financial buffer may still meet the lender's assessment requirements. Another investor who is already near their borrowing limit may find that a relatively modest change in assessed income affects their options.
The most useful approach is to discuss any planned purchase or refinance with your mortgage broker before taking the cash-out. Your broker can assess the timing, check relevant lender policies and explain how the proposed agreement may be treated.
Can a rental income advance help you buy your next investment property?
Access to funds and the ability to service a new mortgage are both important when buying property. You may need enough cash for a deposit, stamp duty, legal fees and other acquisition costs, while also showing a lender that your income can support the new mortgage alongside your existing commitments.
Futurerent can help eligible investors access capital from an existing investment property without refinancing its mortgage. That capital may be useful for a property deposit, buyer's agent fees or other costs associated with a purchase. However, obtaining funds upfront doesn't remove the need to satisfy the next lender's serviceability and deposit requirements, including any rules about the source of funds.
For example, if you have sufficient income to qualify for the mortgage but need additional capital for purchase costs, a cash-out may be worth comparing with savings, redraw, a mortgage top-up or refinancing. If your main limitation is serviceability, you should assess whether receiving less rent during the advance could make that limitation more significant. A mortgage broker can help you compare these options using your actual figures.
What happens if you want to refinance while the advance is active?
Futurerent does not require you to refinance your mortgage to access a cash-out. If you choose to refinance later, though, the new lender may review the Futurerent arrangement when assessing the property and your financial position. It may ask for the agreement, property management statements and a clear explanation of how the rent is distributed.
The lender's response will depend on its policy and your particular circumstances. You shouldn't assume the arrangement will be ignored simply because it doesn't appear as a hard credit enquiry or an increase to your mortgage balance. It's sensible to disclose the arrangement and let your broker establish what supporting information is required.
If the timing of your refinance is flexible, consider whether it makes sense to complete it before entering an advance or after the relevant rental allocation has ended. The right sequence depends on the expected financing benefits, the cost of waiting and the terms of the advance.
Does borrowing capacity improve once the Futurerent arrangement ends?
When the agreed rental allocation ends, more of the property's rent may again become available to you, assuming the tenant continues paying the same rent and there are no other arrangements affecting it. A lender assessing your mortgage application at that stage may take the changed cash flow into account, subject to its lending policy and verification requirements.
There is no automatic reset to a particular borrowing limit. Mortgage rates, your income, living expenses, debts and property performance may all have changed by then. If you intend to borrow after the agreement finishes, ask Futurerent for confirmation of its completion and keep recent rental statements to help your broker document the updated position.
What should you check with your mortgage broker before taking a cash-out?
If another property purchase or refinance is part of your plan, speak with your broker while you are still comparing funding options. A useful review should cover the cash you need today, the impact on your rental income and what your next lender is likely to assess.
- Your current borrowing position. Ask for an estimate based on your existing mortgages, rental income, other income and expenses, using current lender policies.
- The proposed rental allocation. Share the indicative Futurerent amount, expected portion of rent allocated and proposed term so the assessment reflects the actual arrangement.
- Lender treatment. Ask whether lenders on your shortlist will assess reduced available rent, an ongoing commitment or another aspect of the agreement.
- Deposit and source-of-funds requirements. Confirm what evidence the next lender will require if you intend to put cash-out funds towards a purchase.
- Purchase or refinance timing. Consider whether your funding and mortgage plans should be completed in a different order.
- Your financial buffer. Review how much rent you'll retain for mortgage payments, property expenses, vacancies and unexpected repairs.
It can also help to prepare the property's lease, recent rental statements, current mortgage statements and a copy of the proposed cash-out terms. Accurate information makes it easier for your broker to have a useful discussion with lenders before you commit.
How Futurerent works for Australian property investors
Futurerent lets eligible investors cash out up to $100,000 from an investment property, or up to $500,000 across multiple properties, without refinancing their existing mortgages. Approval is based on the property, and investors don't need to provide personal income and expense statements as part of Futurerent's assessment. Once approved and the required steps are completed, eligible investors can receive their funds in 2 business days.
Futurerent works with the property manager, who continues collecting rent from the tenant as usual. An agreed portion of that rent is directed to Futurerent over the term, and the remaining rent continues to the investor. The arrangement has an upfront setup cost and a fixed cost incorporated into the agreed rental income allocation, so you should review both the total cost and the change to your ongoing property cash flow before proceeding.
Investors use Futurerent for a range of purposes, including renovations, property-related expenses, capital buffers and future purchases. If you're considering a new mortgage, it's worth discussing your plans with your broker and comparing the cost and cash-flow implications of the available options. You can read more about the product in our guide to rental income advances.
Frequently asked questions
Does applying for Futurerent affect my credit score?
Futurerent uses a soft credit check with your consent. According to its published product information, this does not create a hard credit enquiry or affect your credit score. Another lender may still assess your current financial position and the available rent when considering a new mortgage application.
Will a bank treat a rental income advance as a loan?
Futurerent is structured differently from a traditional mortgage or personal loan. However, you should not assume every lender will classify or assess the agreement in the same way. Your broker should confirm how a particular bank treats the rental allocation and any other relevant obligations when calculating serviceability.
Can I get another home loan while using Futurerent?
Potentially, yes. Your ability to qualify will depend on the lender's assessment of your income, financial commitments, property position and the Futurerent arrangement. There is no universal approval or refusal rule simply because you have accessed rental income upfront.
Will Futurerent reduce the rental income a bank counts?
It may. A future lender could consider the portion of rent allocated to Futurerent when determining the rental income available to service the mortgage. The approach depends on the lender, and some lenders may request additional documents or treat the allocation differently.
Can I use a Futurerent cash-out as a deposit for another property?
Eligible investors can use their Futurerent funds for a range of purposes, including purchase-related costs. Whether a mortgage lender accepts those funds towards a particular deposit, and what evidence it requires, are separate questions. Check the lender's source-of-funds and deposit requirements with your broker before committing to a purchase.
Should I arrange Futurerent before or after my next mortgage?
The timing depends on why you need the cash and how close you are to applying for another mortgage. If a purchase or refinance is imminent, getting broker advice first may help you understand the lender's assessment and compare the costs of different options. If your next purchase is further away, you can consider how the rental allocation fits your longer-term cash-flow plans.
Understand your next mortgage position before accessing capital
A rental income advance can give property investors access to capital without changing an existing mortgage. It may also change how much rental income is available during the agreement, which can matter when another lender assesses a future application.
If you have another purchase or refinance in mind, start by understanding your current borrowing position and what would change after the cash-out. Comparing the options with your broker can help you preserve flexibility and make a decision that suits both your immediate plans and your longer-term property strategy.
Want to explore how much capital you could access from your investment property? Use the Futurerent cash-out calculator to see an indicative amount, the costs and how the proposed arrangement could affect your rental income.
This article provides general information and does not constitute personal financial, credit, legal or tax advice. Lending criteria vary. Speak with your mortgage broker and other relevant qualified advisers about your circumstances before making financial decisions.