If you own an investment property with substantial equity, you may be considering whether some of that value could help reduce the interest you pay on your mortgage. One option is to access capital from the property and place it in an offset account linked to your home loan or investment property mortgage.
It's possible to do this, provided you can access the capital and your mortgage has an eligible offset account. But the interest you save is only part of the calculation. You'll also need to consider the cost of accessing the funds, how long you intend to keep them in the offset and the effect on your ongoing rental income or mortgage repayments.
You can use capital accessed from an investment property to top up an eligible offset account. Whether it's worthwhile depends on your mortgage rate, the funding costs, the amount you can keep in the account and your wider financial goals. For some investors, the main benefit may be having accessible capital while continuing to hold their property. If your goal is simply to reduce mortgage interest, the numbers deserve a particularly close look.
How does a mortgage offset account work?
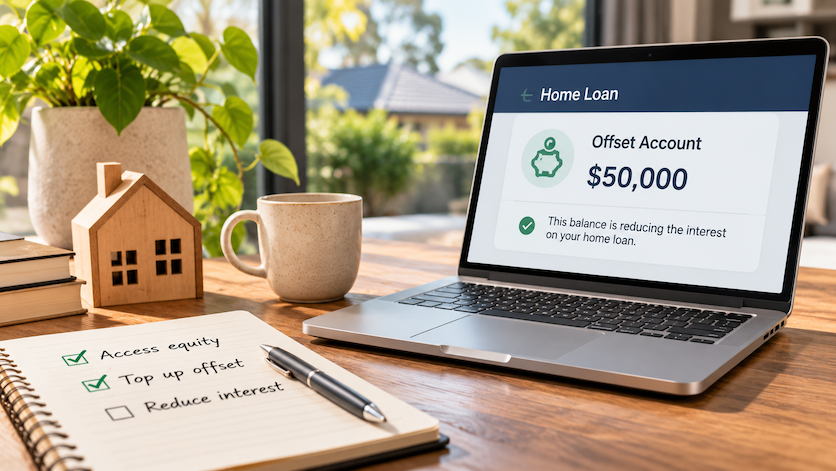
An offset account is a bank account linked to an eligible mortgage. Its balance reduces the amount of the mortgage on which interest is calculated. You can generally use the money for everyday transactions, so it remains accessible while helping reduce interest charges.
For example, if you have a $500,000 mortgage and keep $50,000 in a 100% offset account, the lender generally calculates interest on $450,000 instead of $500,000. At an assumed mortgage rate of 6.50% per annum, maintaining that extra $50,000 throughout the year could save approximately $3,250 in interest, before any tax implications. The actual saving will depend on your daily account balance, mortgage terms and rate changes.
According to Moneysmart's guide to mortgage offset accounts, most home loans calculate interest daily, and some lenders charge additional fees or a higher interest rate for offset features. It's worth checking that the account is correctly linked and that you have a full offset, as some products offer only a partial offset.
How can you access capital from an investment property?
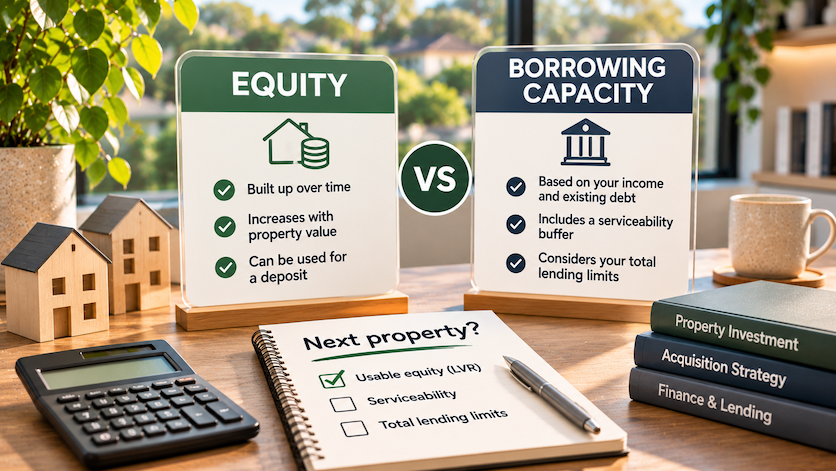
Property equity is the difference between the property's current market value and the amount you owe against it. If an investment property is worth $900,000 and its mortgage balance is $550,000, you have approximately $350,000 in equity on paper. That doesn't mean the entire amount is available to withdraw, because the amount you can access depends on the funding option and its eligibility requirements.
With a bank, you may be able to access some equity by increasing your mortgage or refinancing. The lender will generally consider the property value, your existing debt, income, expenses and borrowing capacity. You could then place any funds released into an offset account, provided the account and loan structure allow it. Remember that releasing equity through a mortgage top-up increases your debt and its associated costs.
Futurerent provides another option for eligible Australian property investors. You can cash out up to $100,000 per investment property, or up to $500,000 across a portfolio, without refinancing your existing mortgage. Futurerent provides capital upfront in exchange for an agreed portion of future rental income, typically over three years. This means you can put the upfront capital into an offset account, but you'll receive less rental income during the agreement and pay Futurerent's fixed funding and setup costs.
For a broader explanation of the alternatives, see our guide to accessing capital from your investment property.
Can you top up the offset on your home or investment property?
In principle, you can deposit available money into an offset account linked to an eligible mortgage, whether the property behind that mortgage is your own home or an investment property. The important distinction is which loan the offset account is linked to. Money deposited into an offset account linked to your family home reduces interest on that home loan. Money placed in an offset linked to your investment mortgage reduces interest on that investment loan.
Offset account linked to your own home
Many investors have a mortgage on their home as well as one or more rental properties. If you access $50,000 from an investment property and deposit it into an offset linked to your owner-occupied home loan, you may reduce the interest charged on that home loan without changing its principal balance. Your offset money remains available if you need it for another purpose.
Owner-occupied home loan interest is generally a private expense and isn't tax deductible. That makes reducing the interest potentially valuable, but you still need to consider the cost of obtaining the $50,000 and whether those funds could be used more effectively elsewhere.
Offset account linked to an investment property
You may instead prefer to place the money in an offset linked to your investment property mortgage. The bank's interest calculation works in much the same way, although the tax consequences can differ. Where mortgage interest would otherwise be deductible, reducing the interest charged also generally reduces the interest deduction you can claim.
The ATO's ruling on loan account offset arrangements explains that deductions for interest on a deductible loan cannot exceed the reduced amount of interest actually incurred. The tax treatment of a Futurerent cash-out and its costs is a separate question, so ask your accountant to review your circumstances before relying on any assumed tax outcome.
How much interest could an extra $50,000 in your offset save?
A simple starting calculation is the additional average offset balance multiplied by your mortgage interest rate. If you kept an extra $50,000 in a full offset account for an entire year at a mortgage rate of 6.50%, the potential interest saving would be approximately $3,250. At 6.00%, it would be approximately $3,000; at 7.00%, approximately $3,500.
Those figures assume the entire $50,000 remains in the account for the full year, that the loan balance is large enough to be fully offset by that amount and that the rate stays unchanged. If you withdraw $20,000 for a repair after three months, you'll save less interest over the remainder of the year. If your mortgage is principal and interest, a reduced interest charge generally means more of your scheduled repayment goes towards principal, although the lender may handle repayments differently depending on your terms.
An offset account is especially useful when you already have savings available. When you're paying to access additional capital, you need to compare the interest benefit against the total funding cost before deciding whether the strategy makes financial sense.
Does topping up your offset with released capital actually save money?
Consider an investor who wants to cash out $50,000 from an investment property and keep that amount in an offset account linked to their home loan. Assume the home loan charges 6.50% per annum, the offset account provides a full offset and the investor can keep all $50,000 in the account for three years.
For the funding side of this example, assume a Futurerent rental income cost of 8.00% per annum on the $50,000 cash-out over three years, plus the currently published $3,900 upfront setup cost for this cash-out amount. The 8.00% rate is an illustrative pricing assumption, and investors should use their actual Futurerent quote and calculator results before making a decision.
In this example, keeping $50,000 in the offset for the full three years produces approximately $9,750 in gross mortgage interest savings. The assumed rental income cost and upfront setup cost total $15,900, leaving a difference of around $6,150 before tax considerations or any other benefits of having the funds available.
If the only objective is to earn interest savings through the offset, this example doesn't produce a net financial saving. The upfront capital may still be useful for other reasons, such as maintaining a reserve for a major expense or avoiding a disruptive mortgage restructure, but those benefits need to be assessed on their own merits. This simplified comparison also assumes that the investor would otherwise have no extra $50,000 in the offset. It doesn't model an alternative where future rental income is gradually saved into the offset instead.
What happens to your rental income when you use Futurerent?
A Futurerent cash-out is provided upfront, while an agreed portion of the property's future rent goes to Futurerent through the property manager. That allocation covers the amount advanced and the fixed rental income cost over the agreed term. The remainder of the rent continues to go to you, and your existing mortgage remains in place.
Using the same illustrative $50,000 cash-out, an assumed total of $62,000 in future rent would be allocated to Futurerent over 36 months. That works out to about $1,722 per month, or approximately $397 per week on average. If the investment property earns $750 per week and stays tenanted throughout the period, roughly $353 per week would remain before management fees, mortgage payments and other expenses. The $3,900 setup cost is assumed to be paid separately upfront.
This is a simplified calculation to demonstrate the cash-flow impact. Your actual rental allocation will depend on the quote, property, rent and selected term. It's important to model the rent you'll continue receiving, particularly if that income currently covers a large part of the investment property's mortgage and holding costs. Futurerent's published guidance also explains that allocations pause when no rent is collected, without increasing the fixed agreed total cost because of a vacancy.
When could topping up an offset with property capital be worth considering?
There are circumstances where accessing capital can provide more than an interest saving. For example, an investor might want to keep money available for planned renovations, a property purchase or a known expense while continuing to reduce home loan interest until the funds are needed. Having accessible capital may also reduce the pressure to sell an investment property when a significant bill arrives.
Even then, the key consideration is the value of having that money available compared with what it costs to access. If the funds are likely to be spent within a few months, the offset interest savings may be relatively small. If the money is needed for a specific purpose, compare the cost of funding that purpose directly with the cost of accessing capital early and holding it in the offset.
For investors whose main concern is keeping enough funds available for unexpected costs, our investment property cash-flow guide explains how to review holding costs and plan for changes. A useful buffer should be based on the property's actual risks, rather than how much capital you can access.
When might another option make more sense?
If you already have accessible savings, putting those savings into a suitable offset account may be considerably cheaper than paying to access additional capital. It is also worth speaking with your lender or mortgage broker about your existing mortgage rate, offset features and whether a redraw facility or a bank top-up would better suit your needs.
Refinancing or increasing a mortgage can involve more paperwork, eligibility checks and a change to your borrowing arrangements. However, it may have a lower total cost than a rental income advance in some situations. Compare fees, loan terms, repayment commitments and the interest you could pay over the period you actually expect to use the money. A lower annual rate does not tell you the complete cost if it comes with a much longer borrowing term.
If your rental property is already difficult to hold because its ongoing expenses exceed your available income, consider the impact of receiving less rent during a Futurerent agreement. The upfront cash might address a defined immediate expense, but it will not automatically make an ongoing shortfall affordable. Reviewing the property's finances before adding a funding commitment can help protect your longer-term plans.
How to decide if using investment property capital for your offset makes sense
- Check your offset arrangement. Confirm which mortgage it is linked to, whether it provides a full offset and whether account fees or a higher mortgage rate apply.
- Work out the capital you need. Decide whether you want a general reserve, funds for a known expense or a longer-term offset balance. Those purposes may call for different amounts and funding periods.
- Estimate the interest savings. Use the mortgage rate and the balance you realistically expect to keep in the account, rather than assuming the entire cash-out will remain untouched.
- Compare the complete funding cost. Include setup costs, the value of rental income allocated to Futurerent, any bank fees and the effect on monthly cash flow. Ask for actual figures over the relevant term.
- Check the tax and borrowing implications. Your accountant can assess tax treatment, while your mortgage broker can help you understand how a reduced amount of available rental income might affect future lending applications.
If you are comparing options, calculate the amount you would have available immediately, what it would cost over your expected period of use and what you would have left each month. That gives you a better basis for deciding whether the extra flexibility is worth paying for.
How Futurerent can help you explore your options
Futurerent allows eligible Australian property investors to cash out up to $100,000 per investment property, or up to $500,000 across their portfolio, without refinancing. The agreement provides capital upfront in exchange for a fixed portion of future rental income, typically over three years. Your tenant continues to pay rent through your property manager as normal, and the manager directs the agreed portion to Futurerent.
Futurerent uses a property-based approval process and a soft credit check that does not affect your credit score. Eligible investors can receive funds in as little as 2 business days after approval. There is a setup cost and a fixed rental income cost, so it's important to review both the upfront amount and the rent you'll continue receiving before proceeding.
If you are thinking about putting released capital into an offset account, start with the numbers. The Futurerent cash-out calculator can give you an indicative cash-out amount, pricing and rental income allocation so you can compare the arrangement with the potential interest savings and other funding options.
Frequently asked questions
Can I use investment property equity to reduce the interest on my home loan?
Potentially, yes. If you access capital from an investment property, you may be able to place it in an eligible offset account linked to your home loan. The offset can reduce the interest charged while the funds remain in the account. You'll need to compare the interest savings with the cost of accessing the capital and check that the arrangement fits your mortgage and tax circumstances.
Can I top up my offset account without refinancing my investment property?
Yes, if you already have accessible savings, you can usually deposit them into an eligible offset without refinancing. Futurerent may also allow an eligible property investor to access capital without changing their existing mortgage. An agreed portion of future rent goes to Futurerent, so consider the upfront cost and the effect on rental income before deciding.
Is an offset account better than paying extra off my mortgage?
Both can reduce mortgage interest, but they work differently. An offset generally keeps your money in a separate accessible account, while extra mortgage payments reduce your loan principal and may be accessible through redraw only under the loan's conditions. Compare account fees, access rules, tax implications and the way each option fits your plans.
Will topping up an investment property offset reduce my tax deductions?
If the interest on your investment mortgage is deductible, an offset generally reduces the interest you actually incur and therefore the amount of interest you can deduct. The final tax result depends on your circumstances, and the tax treatment of any money used to top up the offset may be separate. Ask your accountant to review the loan and funding arrangements.
Does Futurerent affect my borrowing capacity?
Futurerent does not change your existing mortgage or affect your credit score. However, a future lender may consider the portion of rental income allocated to Futurerent when calculating your ability to service a mortgage. Speak with your mortgage broker if you plan to apply for further finance.
Understand the numbers before topping up your offset
An offset account can be a useful place to keep accessible capital while reducing mortgage interest. If you already have the cash available, using an eligible offset may be straightforward. If you need to access capital from an investment property first, the decision requires a closer look at funding costs and the effect on your rental income.
For some investors, accessing money without refinancing can provide flexibility at an important time. The strongest decision is the one supported by your actual figures, including how much interest you may save, how much the capital costs and whether your investment property remains comfortable to hold.
See how much capital you could access from your investment property. Use the Futurerent calculator to explore an indicative cash-out and compare the numbers before deciding what suits you.
This article provides general information only and is not financial, tax or legal advice. Product eligibility, pricing and individual outcomes vary. Consider seeking independent advice from an appropriately qualified professional before making funding or property investment decisions.